14 September 2026, 15:42
Loading...
Analysis: Czech Republic faces no gas shortage risk, but return to February prices remains distant

oEnergetice.cz, ČTK
5 April 2026, 09:53
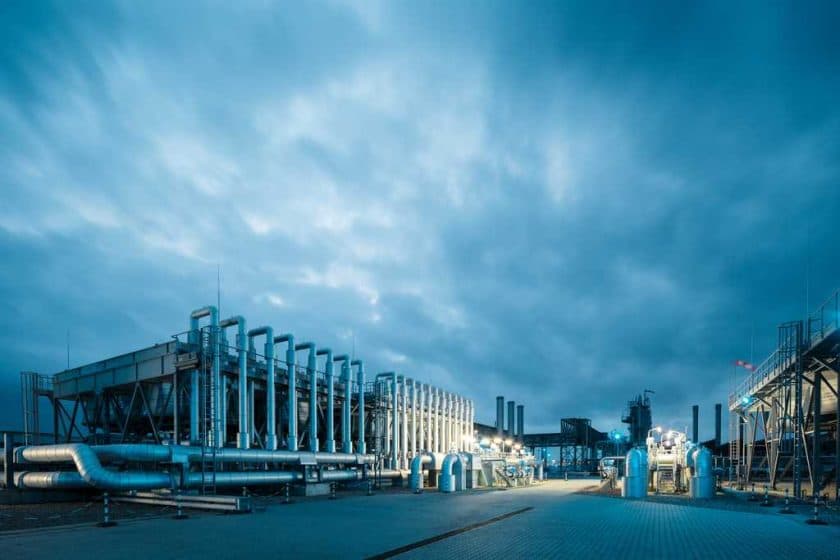
Neither the Czech Republic nor Europe faces a risk of gas shortages next winter. However, a return to price levels seen before the start of the conflict in the Middle East is now out of sight. The current development of the Iran conflict also points to longer-term impacts on gas prices. The commissioning of terminals planned in the US this year will therefore be crucial. This follows from an analysis by consultancy EGU.
"Despite the current halt in the rise in gas prices, which almost doubled during March compared with the previous month, the prospects of a significant decrease this year are not very likely. This is mainly due to the dynamics of the conflict, which is moving from an expected swift military operation into a phase of random armed attacks across the Persian Gulf region, without the necessary diplomatic negotiations," said EGU project director Michal Kocůrek.
Given the impact of the conflict on the global liquefied natural gas (LNG) market, EGU has prepared three price-development scenarios depending on when LNG exports from Qatar and the United Arab Emirates resume.
Gas prices are currently around 42 euros per megawatt-hour (MWh). Under the optimistic scenario, which assumes an outage of around two to three months, the average price for this year would be approximately 41 euros per MWh. Prices could then be expected to return to normal as early as next year. However, if the blockade were to last until autumn, the average price for this year would rise to 57 euros per MWh, with the market likely returning below 40 euros per MWh only in 2028.
The worst-case scenario of a year-long closure assumes an average price of 78 euros per MWh for this year, with possible short-term spikes above 100 euros and persistently high prices in subsequent years. This scenario also assumes permanent damage to part of Qatar's infrastructure and an ongoing security risk.
"Any scenario for the development of the conflict indicates complications associated with this year's injection of gas into storage facilities. Sooner or later, traders will fill storage sites to a certain extent. For the standard process of filling storage facilities and reaching 80 percent of capacity in November, it is advisable to start injections towards the end of April. If imports were not restricted, it would technically be possible to reach this capacity even if injections began at the end of June," noted EGU strategy director Michal Macenauer.
According to EGU, the disruption of supplies from the Persian Gulf region represents barely three percent of global consumption, and the European market therefore still has sufficient capacity to secure the necessary supplies.
Secured supplies for customers have also been confirmed by innogy, the largest natural gas supplier in the Czech Republic. "We already have sufficient gas secured for our existing customers. However, prices for new customers will be determined by developments on the European wholesale market in the coming months," said spokesman Pavel Grochál.
EGU notes that Norway is the EU's main gas supplier and is also expecting a slight increase in exports this year. Increasing existing supplies from Algeria is also under consideration. However, the commissioning of terminals planned in the US this year would have a decisive impact.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.
Sdílejte článek prostřednictvím:
You might also like
14 September 2026, 13:46
14 September 2026, 11:30
14 September 2026, 10:47