Capacity market offers less support for Polish batteries. Investors seek certainty from traders

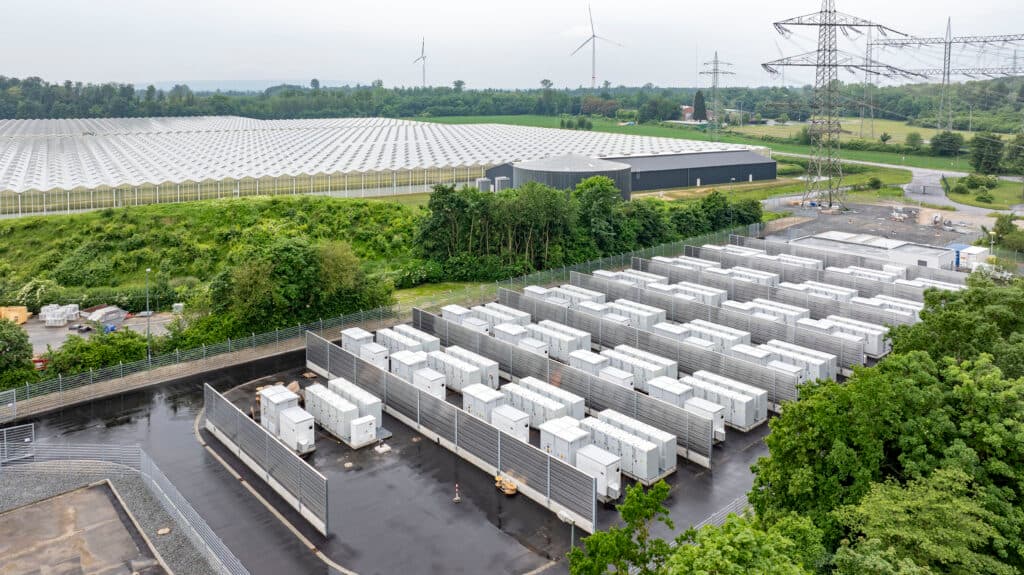
Poland’s capacity market helped get large battery projects off the ground, but its contribution to new investment is changing. Owners are therefore seeking long-term contracts alongside payments for available capacity, giving them more predictable returns and making projects easier to finance. Recent moves by Actis, DRI, Greenvolt and Statkraft are examples. They show that batteries in Poland are becoming not only part of the energy infrastructure, but also assets whose value depends on who can trade their flexibility, and on what terms.
Poland’s capacity market rewards operators for making capacity available to the grid when needed. For a project with high upfront costs, a long-term contract can provide a stable revenue base, supplementing income from electricity trading and providing flexibility.
Poland’s capacity mechanism uses a correction factor to determine what share of their capacity participants can offer in an auction. In Poland’s auction for delivery from 2030, the factor for batteries was 13.39 per cent; a year earlier it was 60 per cent and two years earlier 95 per cent.
The auction itself cleared in the second round at a price of 465.02 zlotys (2,585 Czech crowns) per kilowatt per year, compared with 223.77 zlotys (1,244 crowns) in the previous year’s auction. A higher price therefore does not automatically mean higher overall revenue for batteries. The volume of capacity eligible for payment also matters.
The importance of capacity contracts nevertheless remains clear. R.Power, a leading developer in the Polish market, secured 17-year contracts in the auction for delivery from 2030 for five battery projects with a combined output of 1,012 MW and capacity of 4,032 MWh. They must begin operating by 2030 at the latest.
A long-term contract can provide a project with an important revenue base. However, the gradual reduction in eligible capacity due to the correction factor limits the potential returns from the capacity mechanism. Investors therefore need other ways to stabilise returns.
Traders take on some of the market risk
One option is a tolling agreement. Under this arrangement, a trader gains the right to decide when the battery charges and when it sells electricity, while the owner receives more predictable income. Statkraft and Greenvolt Power have signed a 10-year agreement for the Ełk and Turośń Kościelna projects, each with output of 200 MW and capacity of 800 MWh.
Statkraft will manage their charging and discharging in energy and flexibility markets. Greenvolt will retain the revenue from Poland’s capacity market, making the agreement an additional source of long-term, predictable returns. The companies described it as the largest publicly announced agreement of this type in the European Union to date. It is also Statkraft’s first major battery contract in Poland.
For an investor, it is important that such an agreement can reduce uncertainty around trading revenues. But it is not free insurance: if the trader controls the battery’s operation, it also takes a share of its potential market revenues. The specific financial terms of the Greenvolt-Statkraft agreements have not been disclosed.
The R.Power group, mentioned above, offers a different investment model. According to a Polish media outlet, it signed a 10-year battery optimisation agreement with a price floor for the Dzięgielewo project. This arrangement can combine a minimum guaranteed income with the opportunity for the owner to benefit from revenues above a set threshold. However, publicly available information does not allow the financial terms of this agreement to be compared with those of a pure tolling arrangement.
Infrastructure funds enter projects under development
More predictable returns help explain why infrastructure investors are also taking an interest in battery projects. Actis acquired from DRI the 112 MW Kozienice project, with capacity of 518 MWh and ready for construction, and signed an agreement for the 132 MW Trzebinia project, with capacity of 623 MWh, which is due to be transferred after commissioning.
According to Actis’s announcement, both projects have 17-year, inflation-indexed capacity market contracts. This means their economics do not depend solely on future electricity prices and revenues from optimising operations. The projects’ different stages also show that an investor can enter either a project ready for construction or an asset that is still awaiting completion.
Poland’s battery market is moving beyond simply securing capacity revenues towards a more careful balance of returns and risks. For investors, the combination of a long-term contract, technical readiness and the ability to operate a battery efficiently is important.
Czech auction to start under different rules
Poland’s experience offers an interesting example for Czechia, which is preparing a capacity mechanism. The European Commission approved it on 16 July 2026 as the first mechanism under the CISAF framework. The Czech system is set to run for ten years, while individual capacity contracts can last up to 15 years.
The mechanism is open to generation sources, storage, cross-border capacity and demand response. Capacity will be procured through competitive auctions. The first delivery period is due to run from November 2030 to October 2031. Costs will be covered by consumer levies, and the European Commission estimated the total budget at 3.1 to 6.2 billion euros, depending on the auction results and grid needs.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.