23 October 2026, 11:01
Loading...
European hydrogen runs into reality: without buyers and networks, subsidies are not enough

Jan Budín
23 October 2026, 10:30
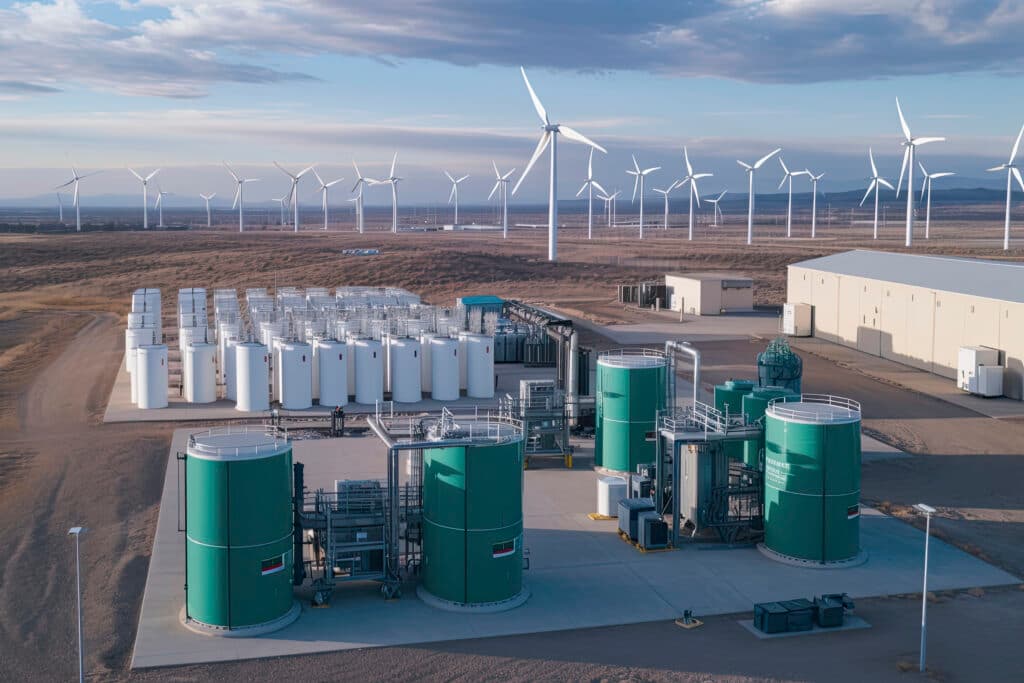
The European debate on hydrogen is shifting from ambitious targets to the question of whether individual projects can actually be financed and connected to buyers. A report by the Oxford Institute for Energy Studies and German association BDEW warns that production capacity alone, or subsidies, will not create a market. What matters is the interplay of demand, infrastructure, long-term contracts and stable rules.
Demand exists, but cheaper fossil-based production has the edge
European hydrogen consumption is currently concentrated primarily in refineries and ammonia production. In 2024, refinery use accounted for approximately 58 % of demand and ammonia for a further 25 %. This is an advantage for cleaner hydrogen, as it can replace a molecule that industry already consumes. But that does not mean existing buyers will voluntarily switch to more expensive production.
According to analyses presented at the seminar, a kilogram of hydrogen produced by electrolysis using wind power under a long-term contract would cost around 4.72 euros in 2030. The report’s authors, meanwhile, estimated the marginal cost of continuing to operate an existing steam methane reforming facility at 1.98 euros per kilogram. Electricity prices and electrolyser utilisation therefore play a crucial role: the fewer hours a facility operates, the harder it is to spread its high investment costs.
Sensitive to political decisions
Future consumption also depends on how stringent emissions limits will be and how competing technologies develop. In one modelled scenario with an emissions cap of 90 %, hydrogen consumption reached 768 TWh in 2040, compared with just 168 TWh in the baseline scenario. The report does not consider these figures to be a forecast. Rather, they show how significantly estimates can change depending on political decisions and assumptions about electrification or the use of hydrogen fuels.
Nor is a political target or announced offtake necessarily guaranteed demand for investors. Of the capacity planned for 2030 tracked by the report, only 7.4 % was accounted for by projects that were operational or firmly committed. For financing, what matters is whether interest turns into a long-term contract with a credible buyer, rather than remaining a non-binding declaration.
That is why the report recommends assessing the entire project, not just the cost of the hydrogen produced. A production facility needs a secure supply of electricity and water, a connection to a network or storage, a buyer willing to sign a contract, and rules that will not change fundamentally during the investment period. An unresolved link in this chain can halt the entire project, even if the other parts make economic sense.
Infrastructure and public support must share the risk
The development of hydrogen networks is a classic coordination problem. Producers and buyers are reluctant to invest without certainty that transport and storage will be available. Infrastructure operators, in turn, find it difficult to justify large investments without sufficiently certain demand. Waiting for demand backed by fully contracted commitments can stall the market, while building far in advance of it risks creating underused assets.
The report identifies industrial clusters, gradual capacity expansion and investments tied to strengthening signals from users as possible ways forward. According to the authors, public support should primarily help with coordination, the risks of first-of-a-kind projects and some uncertainties related to policy measures. It should not, however, take on ordinary commercial risks, such as responsibility for costs or finding customers.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.
Sdílejte článek prostřednictvím:
You might also like
23 October 2026, 06:34