4 November 2026, 14:17
Loading...
Competition between Europe and Asia in the LNG market should be less intense this winter than last year

Jan Budín
22 September 2023, 12:30
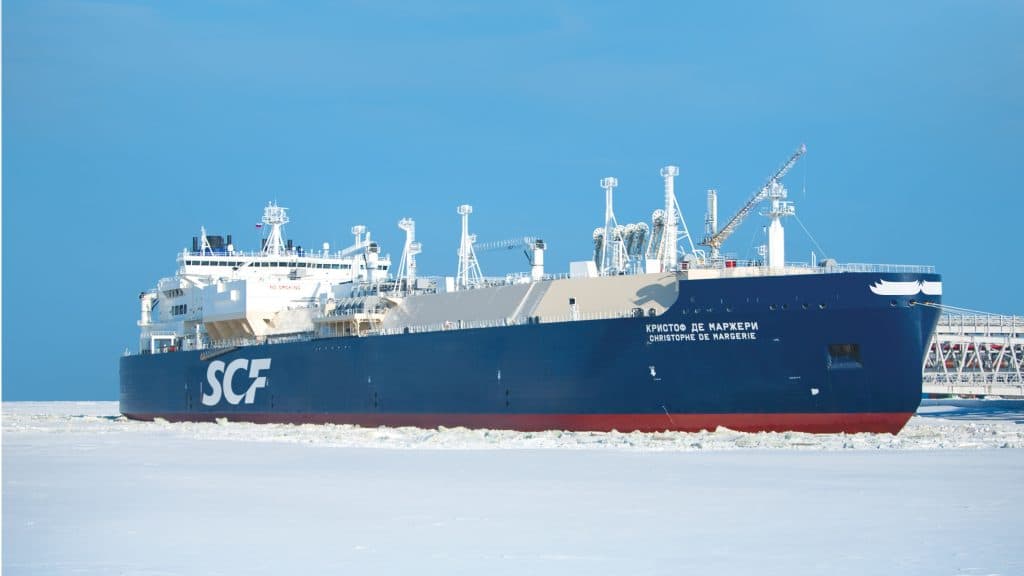
The liquefied natural gas (LNG) market should be considerably calmer this winter than last year. Researchers at BloombergNEF (BNEF) believe this based on current European gas storage levels, the outlook for LNG demand in Asia and a positive outlook for supply. The risks, by contrast, include an extremely cold winter and the threat of strikes in Australia.
BNEF analysts expect winter LNG demand to rise by 4% year on year to 212 million tonnes, with China (up 12% year on year) and Southeast Asia (up 38% year on year) expected to be the main drivers of this growth. Demand is expected to fall in South Korea and Europe.
LNG supply, on the other hand, is expected to rise by 6% year on year to 220 million tonnes, thanks both to the restart of the US Freeport export terminal and to the commissioning of several new terminals in Mexico, Indonesia, Russia and Africa.
"US LNG exports are expected to rise by 17% year on year, mainly due to Freeport's return and higher utilisation of the Calcasieu Pass terminal. Most US terminals will be used more this winter," BNEF said.
BNEF researchers warned, however, that several factors could undermine their outlook for a relatively calm LNG market this coming winter. The main ones include weather, uncertainty about LNG demand in China and gas demand in Europe, as well as supply disruptions.
"Lower-than-expected pipeline gas deliveries from Central Asia could increase LNG demand in China by 1.9 million tonnes. Similarly, lower nuclear power generation in Japan and South Korea could increase gas consumption. A cold winter in northern Asia and Europe could increase demand by 6.1 million tonnes and 14 million tonnes, respectively. A two-week shutdown of Chevron's terminals could reduce supplies from Australia by 1.1 million tonnes," BNEF added, outlining the risks.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.
Sdílejte článek prostřednictvím:
You might also like

4 November 2026, 12:34

4 November 2026, 09:09