12 October 2026, 07:40
Loading...
Who makes solar panels? Chinese quartet continues to dominate the market
Erik Novotný
12 October 2026, 07:40
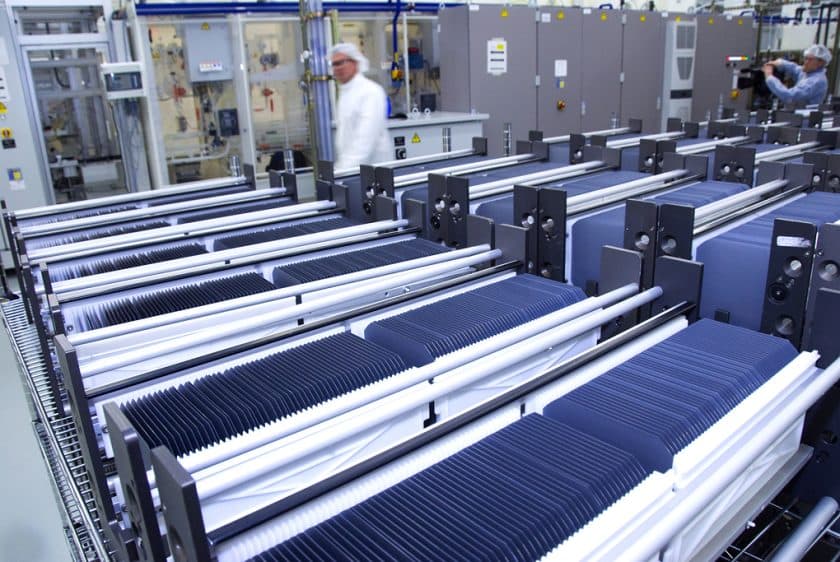
The global photovoltaic market is entering a period of stronger competition and lower capacity utilisation, according to a report by Enerdata. While solar power installations worldwide continue to grow, European panel manufacturers face cost pressures, project cancellations and uncertainty over future manufacturing support.
Four giants still dominate
According to Enerdata’s report The New Global Reality for PV Module Manufacturers – 2026, the 40 largest manufacturers tracked delivered a total of 643 GWp of photovoltaic modules in 2025, down 6% from the previous year. Global installations, meanwhile, reached a record 664 GWp.
At the top remained Chinese companies LONGi, with deliveries of 87 GWp, JinkoSolar with 86 GWp, JA Solar with 70 GWp and Trina Solar with 67 GWp. Year-on-year results fell for three of the four manufacturers. The market shows that even the biggest players are not immune to growing competitive pressure.
Manufacturing capacity remains underused
Global nameplate module manufacturing capacity reached 1,315 GWp, according to Enerdata, but aggregate capacity utilisation fell to around 49%. In 2024, it stood at about 66%. Manufacturers therefore have capacity far in excess of current delivery volumes.
Industrial policy is also shaping the competitive landscape. The report says Chinese subsidies for the solar industry amounted to 3.2% of revenue, compared with an average of 0.9% across 15 other sectors. These differences make it harder for manufacturers in Europe to compete.
Europe installs more, but manufactures less
New installations in the European Union totalled 65.1 GWp in 2025, marking the first year-on-year decline in a decade. Cumulative installed capacity nevertheless rose to 406 GWp.
At the same time, EU module manufacturing capacity fell from 12.6 GWp in 2024 to 10.8 GWp in 2025. Solar cell production stood at around 2 GWp, while production of silicon wafers and ingots in the EU had virtually disappeared. The European market therefore remains dependent on foreign supply chains.
New projects face uncertainty
Uncertainty over financing and regulatory conditions is complicating Europe’s manufacturing ambitions. French company Carbon cancelled a project for an integrated factory with planned production capacity of 5 GWp in May 2026. Chinese company DAS Solar, by contrast, is building a 3 GWp module factory in Mandeure, France.
Other projects are at the planning stage. If the announced investments go ahead, they could significantly increase Europe’s manufacturing capacity.
Competitiveness will be decisive
The European Net-Zero Industry Act (NZIA) sets an indicative target for 2030 of at least 30 GWp of manufacturing capacity at every stage of the value chain. Meeting it will depend not only on building factories, but also on their ability to compete on price and secure stable buyers.
For Europe, the key question remains whether it can combine the rapid expansion of photovoltaics with economically sustainable domestic manufacturing.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.
Sdílejte článek prostřednictvím:
You might also like
11 October 2026, 20:09
11 October 2026, 08:24
10 October 2026, 13:19