25 October 2026, 08:20
Loading...
Record tanker rates push oil and fuel prices higher
Erik Novotný
25 October 2026, 08:20
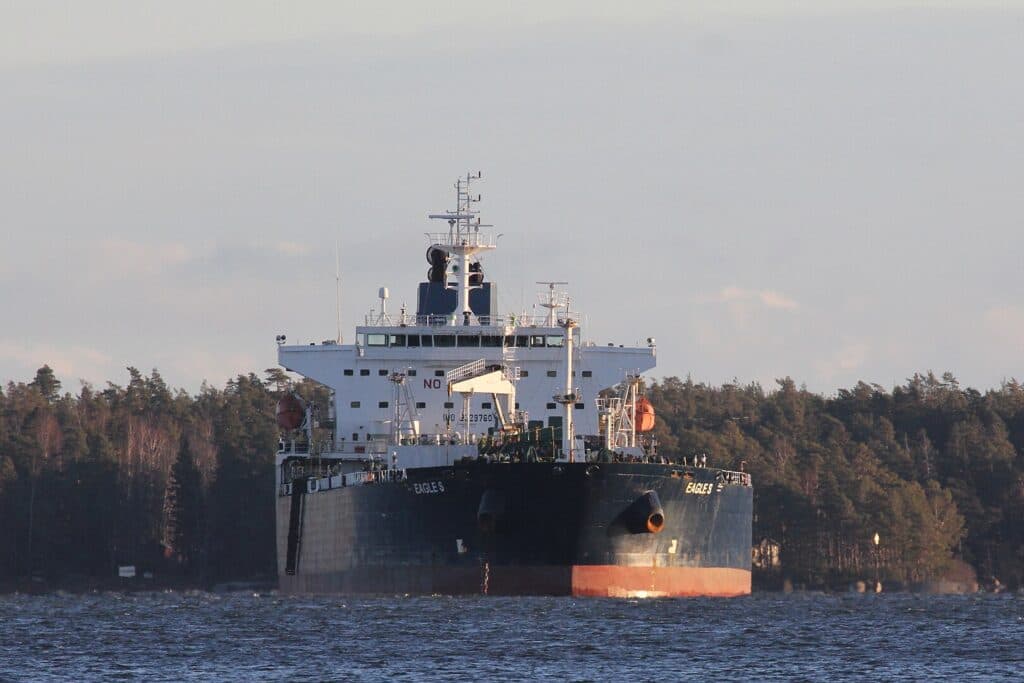
The price of crude oil itself makes up only part of the final price per barrel. According to a new analysis by the International Energy Agency (IEA), tanker shipping rates surged to record highs in September. This is making oil and fuel deliveries more expensive around the world, with the higher costs gradually feeding through to consumer prices.
Transport usually accounts for only a small share of the final price of oil. But when shipping costs rise sharply, the costs accumulate throughout the supply chain. Markets have been roiled by the war in the Middle East since February. Attention has focused on the availability of oil from the Persian Gulf and the reopening of the Strait of Hormuz, while freight rates have risen almost unnoticed. In mid-October, shipping oil by large tanker from the Gulf to Asia cost more than USD 37 per barrel—over five times the pre-war rate.
A bottleneck with global consequences
Congestion near Hormuz, diverted trade flows and increasingly frequent ship-to-ship transfers are lengthening delivery times and reducing fleet efficiency. Tankers tied up on longer routes are in short supply, pushing rates higher. Russia’s aggression in Ukraine had already increased tensions. Sanctions created a shadow fleet operating outside the mainstream market.
The latest wave of price increases was triggered on 11 September by drone attacks on Saudi Arabia’s East-West pipeline, a key route to the Red Sea that bypasses Hormuz. The pipeline was repaired within a few days. But combined with the Houthi blockade of the Bab al-Mandab Strait and rising Chinese purchases, the attacks significantly increased demand for tankers.
Higher costs spread across the fleet
Shipowners are raising rates for smaller vessels, too, including Suezmax and Aframax tankers. Demand for them in the third quarter was roughly one-fifth higher than a year earlier. In mid-October, shipping oil from West Africa to Europe on a Suezmax tanker cost more than USD 22 per barrel, while North Sea Aframax rates had tripled to over USD 6.
The product tanker market is also affected. LR2 vessels are switching to crude oil exports, tightening capacity for diesel and gasoline. The rate for LR1 tankers from the Gulf to Japan was approaching USD 27 per barrel.
Refineries have little room to maneuver
Asia is bearing the brunt of the situation. The daily rate for the largest class of tanker, the VLCC, on the route from the Persian Gulf exceeded USD 1.3 million, pushing the margins of Asian refineries processing Middle Eastern crude into negative territory in September. European refineries had so far absorbed the higher costs with strong margins, but rising oil prices in the second half of September began to put pressure on them.
Replacing Gulf crude with US oil is also expensive. Shipping it costs USD 33 per barrel to Singapore and USD 24 per barrel to Europe. Refineries must therefore choose between more expensive crude, less suitable grades of oil and cutting output. The latter would tighten supplies of diesel and kerosene.
What this means for Europe and Czechia
Czechia receives oil mainly by pipeline, so the direct impact of shipping rates is smaller. But prices at the pump are shaped by the European market for refined products, where any cuts to refinery output will have an impact.
The IEA also warns that even if the situation in the Persian Gulf eases, shipping costs may not fall quickly. Restocking, high exports and inefficient routes will continue to tie up tanker capacity for some time.
Translation disclaimer
This article is a machine translation of the Czech original and has not yet been fully reviewed. In case of any doubt, please refer to the Czech version.
Sdílejte článek prostřednictvím:
You might also like
23 October 2026, 14:38